How We Create Your Pension
A straightforward explanation of how the strategy works, what it costs, and what you can expect.
Finding Your Income Gap
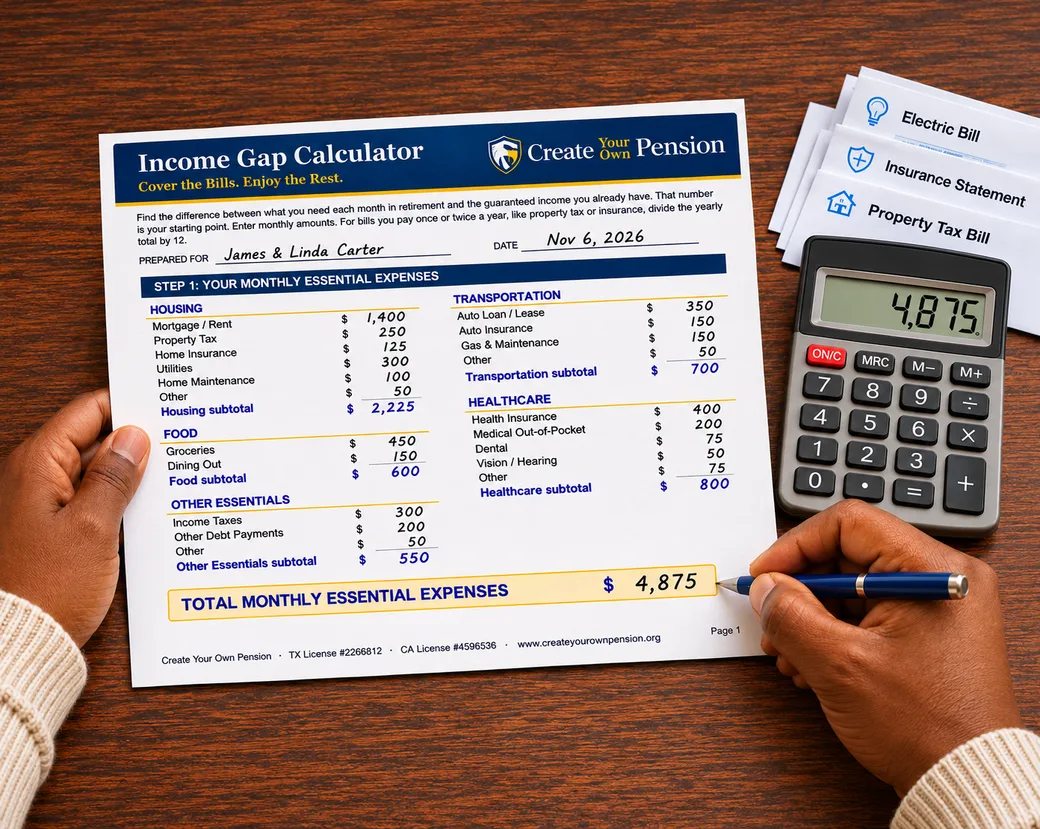
Before we talk about any solution we need to understand your specific situation. That starts with two numbers.
Your essential expenses. Housing, healthcare, food, and transportation. The bills that show up every month regardless of what the market does.
Your guaranteed income includes Social Security, any pension, and anything else that arrives on a predictable schedule regardless of market conditions. If you have not already, create your Social Security account to see your projected benefit.
The difference between the two is your income gap. A gap is not proof that you saved wrong or waited too long. It is simply the distance between what your life will cost each month and what is guaranteed to show up no matter what the market does.
The Gap Is Real. It Is Also Fixable.
Closing the Gap
Here is what that gap looks like for most people, and how a Pension Strategy closes it.

Illustrative example only. Your numbers will vary.
That gap right there is what we are solving for.
Here is where most people stop. They assume it has to come from their portfolio. It doesn't have to.
A portion of your retirement savings can be converted into a Pension Strategy, a contractually guaranteed monthly income stream that covers your essential expenses for life, regardless of how long you live or what the market does. Not all of your savings. Just enough to close the gap.
What a Pension Strategy Actually Is
Our Pension Strategy uses an insurance product called a Fixed Indexed Annuity with an income rider attached to it. That is the technical name. Here is what it actually does.
You allocate a portion of your retirement savings to the strategy. During a deferral period, typically 5 to 10 years, that money grows at a guaranteed rollup rate. You do not have to worry about market performance during this time. The growth is contractual.
When you are ready to turn on income, the insurance company begins paying you a guaranteed amount every month for the rest of your life. It does not matter how long you live. It does not matter what the market does. The income continues.
Want to go deeper? Explore our free guides and tools.
With a Pension Strategy, You Are in Control
You lock in the amount
It cannot be reduced by Congress or any government body.
You decide when income starts
It cannot be delayed by a change in retirement age.
The rules cannot be changed on you
It is not subject to political decisions you have no control over.
Social Security is your baseline income. Your Pension Strategy builds on top of it. Together they create an income foundation that no market downturn, no political decision, and no change in retirement rules can take away.
That means you’re never forced to sell investments in a down market just to pay the bills. That risk, called sequence of returns risk, is the single greatest threat to a retirement portfolio, and your Pension Strategy takes it off the table for your essential expenses.
What that does to the rest of your portfolio is remarkable. It no longer has to carry the full burden of your lifestyle. It can stay invested. It can recover from downturns. It can grow and be used for the things that make retirement genuinely enjoyable.
Travel. Family. Home. Causes you care about.
Same $40,000 Income Gap. Two Different Retirement Jobs
Both begin at age 55 with $500,000 saved. Neither way is wrong, they just organize their money differently.

Her portfolio has two jobs.
- Age 55: $500,000 stays fully invested
- Age 65: Grown to $1,000,000
- Same year: $40,000 a year must come from the portfolio
- The portfolio's job: create the paycheck AND keep growing
Every paycheck depends on what the market is doing.

Her portfolio only has one job: growth.
- Age 55: $266,586 goes to her Pension Strategy. $233,414 remains for growth and flexibility.
- Age 65: Remaining portfolio grown to $466,828
- Same year: $40,000 a year, guaranteed by the Pension Strategy
Her retirement paycheck is separated from market withdrawals.
Hope's dollars do two jobs at once. Helen's do the same two jobs, just divided ahead of time. Neither is wrong, and depending on the market, either sister might end up with more money. But more money was never the goal. Dependable income was, income the market can't touch. Cover the bills. Enjoy the rest.
What Working With Me Looks Like
Simple and transparent, from first call to first paycheck.
Your Income Analysis
A 30-minute conversation about your goals, expenses, savings, and guaranteed income, to find what your current income won’t cover. No paperwork, pressure, or sales pitch.
Exploring Your Options
If a Pension Strategy fits, I’ll show you what it could look like using real numbers from established insurance companies. If it doesn’t fit, I’ll tell you.
The Decision Is Yours
You decide whether a Pension Strategy belongs in your plan and how much of your gap it covers. My job is to explain the options and tradeoffs clearly, not to decide for you.
Implementation and Ongoing Support
I handle everything from application until your Pension Strategy is in place, and I’m here for questions long after. A long-term relationship, not a one-time transaction.
Ready to See What Your Numbers Look Like?
The best way to understand what this strategy could mean for you is a 30-minute Income Analysis.
We map out your income gap, show what a Pension Strategy could look like, and answer every question you have.
No pressure. No obligation.